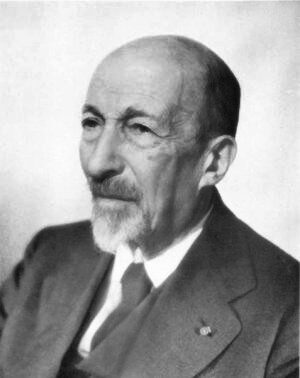
Hadamard matrix
Hadamard matrix is a real square matrix whose all columns (rows) are mutually orthogonal and which only 1 or −1 as entries.
All 1 facts, and where they come from
Facts
1 facts · 0 confirmed by two sources · 0 cited · 1 from one source
Where this comes from
Papalocal keeps its own record. It started from these sources; what each one said is kept here as it was copied, so a change on their side never changes this page by itself. Tap one to read its version.
What Wikidata says · copied November 17, 2026 · revision 2567609762
- Described as
- real square matrix whose all columns (rows) are mutually orthogonal and which only 1 or −1 as entries
- Named after
- Jacques Hadamard
- Wikipedias with a page
- 23
Wikidata item Q1422682 (wikidata.org/wiki/Q1422682), public domain (CC0). Copied 2026-11-17.
What Wikipedia says · copied November 17, 2026 · revision 1376288636
In mathematics, a Hadamard matrix, named after the French mathematician Jacques Hadamard, is a square matrix whose entries are either +1 or −1 and whose rows are mutually orthogonal. In geometric terms, this means that each pair of rows in a Hadamard matrix represents two perpendicular vectors, while in combinatorial terms, it means that each pair of rows has matching entries in exactly half of their columns and mismatched entries in the remaining columns. It is a consequence of this definition that the corresponding properties hold for columns as well as rows.
The n-dimensional parallelotope spanned by the rows of an n × n Hadamard matrix has the maximum possible n-dimensional volume among parallelotopes spanned by vectors whose entries are bounded in absolute value by 1. Equivalently, a Hadamard matrix has maximal determinant among matrices with entries of absolute value less than or equal to 1 and so is an extremal solution of Hadamard's maximal determinant problem.
Certain Hadamard matrices can almost directly be used as an error-correcting code using a Hadamard code (generalized in Reed–Muller codes), and are also used in balanced repeated replication (BRR), used by statisticians to estimate the variance of a parameter estimator.
From the Wikipedia article “Hadamard matrix” (en.wikipedia.org/wiki/Hadamard_matrix), by its contributors, under CC BY-SA 4.0 (creativecommons.org/licenses/by-sa/4.0/). Copied 2026-11-17; not changed.
Confirmed Two sources agree. Cited One source, and it names where it got it. One source One source, without a reference of its own. Sources disagree The sources disagree. We show the best-supported value and keep theirs below.